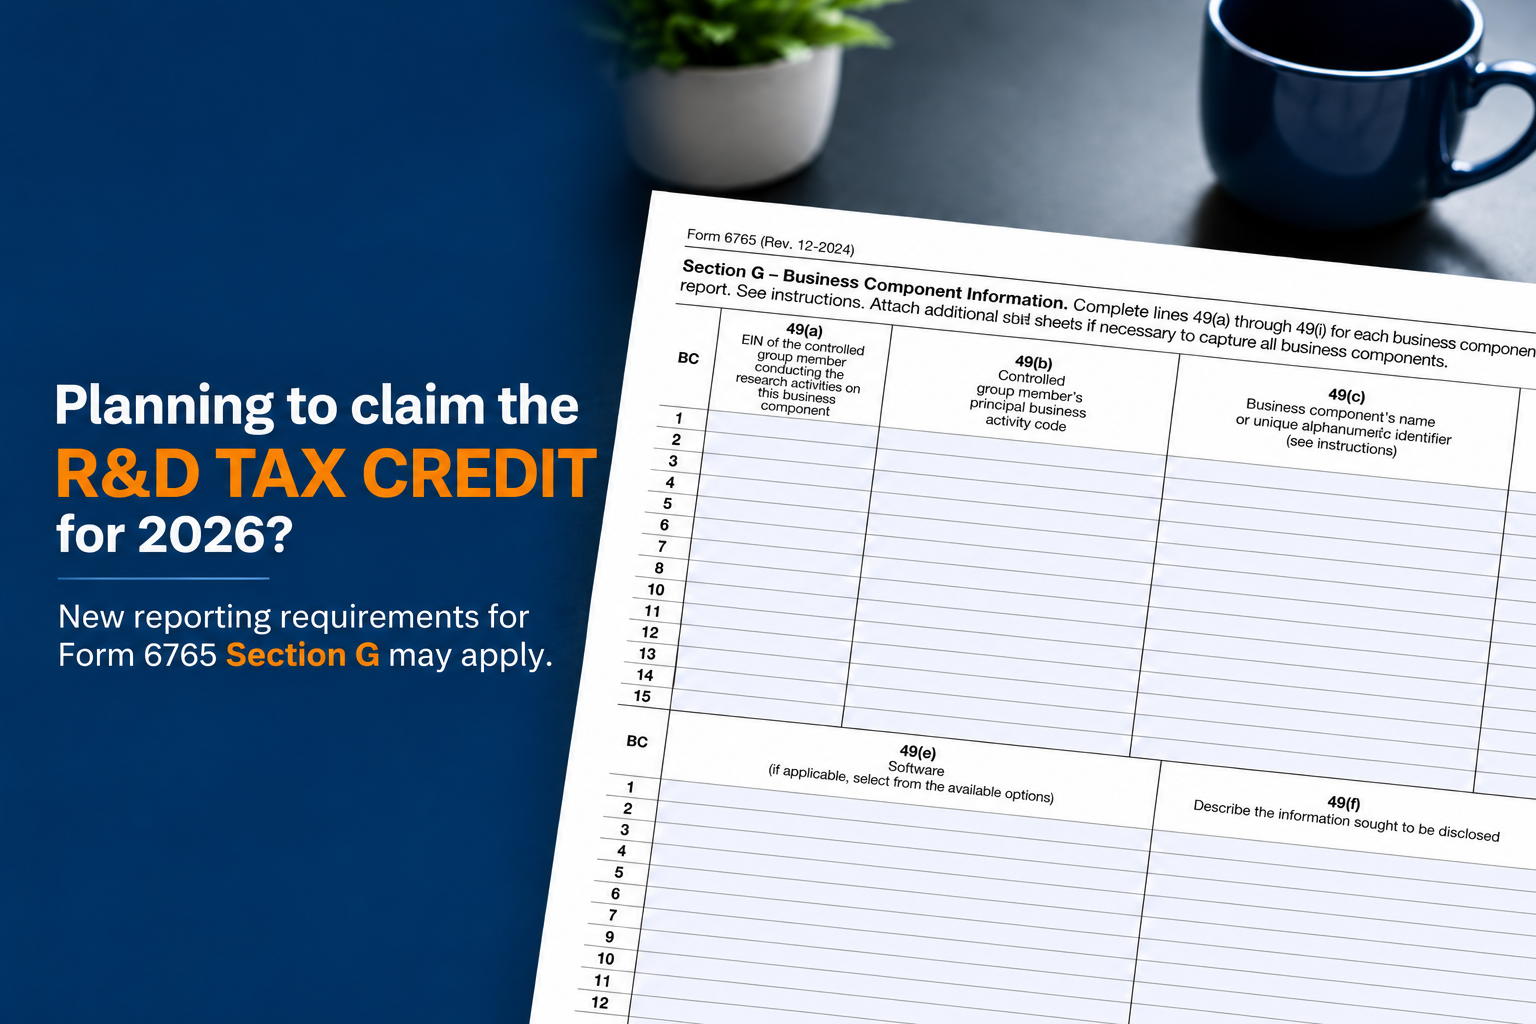
Businesses planning to claim the federal R&D tax credit for 2026 should start preparing for Form 6765 Section G now.
For tax years beginning on or after January 1, 2026, many claimants will need to report qualified research expenses by business component. This could include specific products, processes, software, techniques, formulas, or inventions.
When Section G applies, taxpayers generally must:
- Report business components covering at least 80% of total QREs, up to 50 components.
- Assign wages, supplies, computer costs, and contract research expenses to the appropriate business components.
- Separate wages for performing, directly supervising, and directly supporting research.
- Use project names or identifiers that align with company records.
- Support how the four-part test applies to each business component.
Are there exceptions?
Yes. Section G is not required for every claimant. Exceptions may apply to certain qualified small businesses making the payroll tax credit election and certain original-return filers that meet both the QRE and gross-receipts thresholds.
The key point: This requirement is based on when the tax year begins, not when the return is filed. For calendar-year businesses, it generally starts with the 2026 return filed in 2027.
Organizing projects and expenses during 2026 can make filing more efficient and help create a more supportable R&D credit claim.